

IMF Wants Kenya to Reveal Identities Behind Crypto Transfers

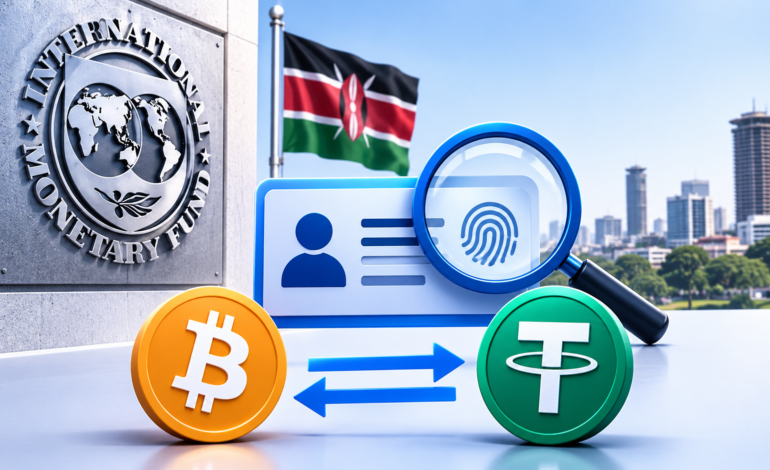
Kenya’s cryptocurrency users could face stricter identity checks as the International Monetary Fund (IMF) pushes the country to require crypto platforms to share information about people sending and receiving digital assets. The proposed changes are meant to fight money laundering, but they also raise important questions about financial privacy and the future of cryptocurrency in Kenya.
For many Kenyans, sending cryptocurrency can be as simple as opening an exchange account, entering a wallet address, and pressing send.
Within minutes, Bitcoin, USDT, or another cryptocurrency can reach someone on the other side of the world.
But behind that transaction, a question is becoming increasingly important to financial regulators.
Who is sending the money, and who is receiving it?
The International Monetary Fund wants Kenya to make that information easier for regulated cryptocurrency platforms and financial authorities to access.
According to a November 9, 2026 report by Business Daily Africa, the IMF has identified a significant weakness in Kenya’s emerging cryptocurrency regulatory framework.
The concern is that cryptocurrency platforms may be required to identify their customers and maintain transaction records without having sufficiently clear legal obligations to exchange that information with other platforms when processing transfers.
To close the gap, the IMF wants Kenya to introduce explicit requirements based on the international Crypto Travel Rule.
If implemented, the rules could change how Kenyans send cryptocurrency between exchanges, particularly when transferring funds to platforms operating outside the country.
However, this does not mean that cryptocurrency has been banned, that every wallet owner must register with the government, or that the identities of all crypto users will become public.
The proposal is more specific than that.
What Exactly Does the IMF Want Kenya to Do?
The IMF wants Kenya to strengthen its laws so that regulated cryptocurrency companies can reliably identify the people behind digital asset transfers.
Under the proposed approach, crypto platforms would be expected to obtain, keep, and securely transmit required information about the sender and recipient of a transaction.
This information could include a customer’s name, account reference, wallet address, and identifying details such as a physical address or national identification number, depending on the applicable rules.
The information would be shared with the financial institution or cryptocurrency service provider receiving the transfer.
Kenya’s Financial Reporting Centre (FRC), which deals with financial intelligence and suspicious transaction reports, would also play an important role in overseeing compliance and accessing information through legally established reporting channels.
The IMF’s central concern is that simply knowing the identity of a platform’s own customers may not be sufficient to detect certain financial crimes.
For example, an exchange in Kenya might know who is sending cryptocurrency from its platform.
But if the receiving exchange does not receive the necessary information about the sender, it could struggle to determine whether the incoming transaction involves a sanctioned person or someone linked to suspicious financial activity.
The IMF reportedly wants this gap addressed through Kenya’s Virtual Asset Service Providers Regulations or another appropriate legal instrument.
The recommendation was reported by Business Daily as coming from a recent IMF technical assistance assessment of Kenya’s crypto rules.
It is important to understand that this is a regulatory recommendation, not evidence that a new requirement has already taken effect for every cryptocurrency transfer in Kenya.
What Is the Crypto Travel Rule?
The name might sound strange, but the concept is relatively simple.
Imagine sending money from your bank account in Kenya to another person’s bank account abroad.
Banks generally collect information about the person sending the money and the person receiving it.
This helps them identify suspicious payments, comply with sanctions requirements, and investigate potential financial crimes.
The Crypto Travel Rule seeks to bring similar obligations to cryptocurrency transfers handled by regulated service providers.
It comes from the Financial Action Task Force (FATF), an international body that develops standards for combating money laundering and terrorist financing.
FATF’s Recommendation 16 addresses payment transparency, while its virtual asset standards explain how these principles apply to cryptocurrency service providers.
In June 2025, FATF updated its payment transparency standards to improve the information accompanying transfers and help financial institutions detect fraud and other financial crimes.
The idea is straightforward.
When a regulated cryptocurrency company sends digital assets to another regulated company, certain identifying information should travel securely alongside the transaction.
Not necessarily on the blockchain itself, but through an appropriate information-sharing arrangement between the institutions.
This is intended to help the receiving company understand where the funds came from and who is supposed to receive them.
What Would This Look Like for an Ordinary Kenyan?
Imagine you live in Nairobi and want to send KSh 50,000 worth of USDT to a friend who uses another cryptocurrency exchange.
Today, the exact process depends on the platforms involved, their existing compliance systems, and the laws that apply to them.
Under a fully implemented Travel Rule system, the process could become more structured.
Your exchange would already have your identity information from the verification process you completed when opening your account.
Before processing a transfer covered by the rule, the platform would also need the required information about the receiving party.
It would then securely transmit the relevant details to the receiving service provider.
The receiving platform could use that information to verify the transaction, perform sanctions screening, and check for suspicious activity.
If the required details were missing or inconsistent, a platform might need to conduct further checks before completing the transfer.
That could mean some users experience additional questions, verification steps, or delays.
However, these are possible practical consequences, not confirmation that every Kenyan sending KSh 50,000 in cryptocurrency will face a new identity-check procedure.
The final obligations will depend on the legal requirements Kenya adopts, the nature of the transaction, and the platforms involved.
But Don’t Crypto Exchanges Already Know Their Customers?
Many do.
If you have ever opened an account with a major cryptocurrency exchange, you may have been asked to provide your name, identification document, photograph, and other personal information.
This process is commonly called Know Your Customer, or KYC.
Its purpose is to help financial service providers establish the identities of their customers.
So why does the IMF want another requirement?
Because knowing your customer and sharing required information during a transfer are not the same thing.
KYC focuses on identifying the person using a financial service.
The Travel Rule focuses on ensuring that required information about the sender and recipient accompanies certain transfers between regulated institutions.
An exchange could have detailed records about all its customers but still lack an effective process for transmitting information to another exchange.
This is the gap the IMF wants Kenya to address.
It is not necessarily asking exchanges to start identifying customers for the first time. Instead, it wants the information-sharing obligations to become clearer and enforceable.
Why Is Kenya Under Pressure to Strengthen Crypto Monitoring?
The IMF’s recommendation comes as Kenya works to improve its reputation in the international financial system.
Since February 2024, Kenya has been on FATF’s grey list.
Being grey-listed means a country is under increased monitoring because of identified weaknesses in its systems for preventing money laundering and terrorist financing.
It does not mean all financial transactions in the country are illegal or suspicious.
Rather, the country has committed to addressing deficiencies under an agreed action plan.
In its October 30, 2026 update, FATF confirmed that Kenya remained under increased monitoring.
The organisation acknowledged progress in areas such as financial supervision, beneficial ownership information, and the use of financial intelligence.
However, it also highlighted remaining work involving transparency and the investigation and prosecution of money laundering.
Kenya’s crypto sector is part of a much larger effort to improve financial oversight.
Cryptocurrency can move across borders quickly, often without relying on traditional international banking channels.
This has made it useful for legitimate businesses and individuals.
But the same characteristics can also attract fraudsters and criminals seeking to move funds between jurisdictions.
For regulators, the challenge is to make suspicious activity easier to identify without unnecessarily disrupting legitimate transactions.
The Travel Rule is one of the tools international authorities believe can help achieve that balance.
Kenya Already Has Crypto Laws. So What’s Missing?
Kenya has made significant progress toward formally regulating cryptocurrency businesses.
The country enacted the Virtual Asset Service Providers Act in 2025, creating a legal foundation for licensing and supervising businesses that provide services involving digital assets.
The government subsequently developed implementing regulations, which were gazetted in July 2026.
The Capital Markets Authority’s regulatory framework lists the Virtual Asset Service Providers Regulations, 2026, while the Central Bank of Kenya previously published the draft regulations for public consultation.
The framework covers areas such as licensing, supervision, risk management, and consumer protection.
But passing a law to regulate cryptocurrency businesses does not automatically resolve every technical compliance requirement.
According to the November 9 Business Daily report, the IMF believes Kenya still needs a sufficiently explicit and enforceable legal obligation for service providers to transmit sender and recipient details during covered digital asset transfers.
This distinction matters.
A legal requirement to maintain records is different from an obligation to send particular information securely to another institution when a transaction takes place.
The IMF is reportedly recommending that Kenya close this gap without delay.
Kenya’s regulatory authorities have also been developing broader financial-sector guidance addressing virtual assets and payment transparency.
The IMF recommendation therefore fits into an existing regulatory reform process rather than representing an entirely new effort to regulate cryptocurrency.
Does This Mean the End of Anonymous Crypto Transactions in Kenya?
Not exactly.
The first thing to understand is that most cryptocurrency transactions are not completely anonymous to begin with.
Bitcoin, for example, operates on a public blockchain.
Anyone can examine transactions, wallet addresses, and amounts transferred.
However, a wallet address does not automatically reveal the real-world identity of its owner.
This is why Bitcoin is often described as pseudonymous rather than anonymous.
A wallet address might appear as a long combination of letters and numbers, without publicly displaying the owner’s name.
But if an exchange knows who controls that wallet, or investigators can connect the address to other identifying information, the transaction may become traceable to an individual.
The Travel Rule would increase the amount of identifying information exchanged between regulated platforms.
That could make it easier for authorities to connect certain transactions to real people.
But it would not automatically attach a person’s national ID number to every transaction visible on a public blockchain.
Nor does it mean anybody browsing a blockchain explorer would suddenly see the names of the people behind all transfers.
The information would generally be exchanged through regulated channels, subject to applicable legal safeguards.
What About Trust Wallet, MetaMask, and Other Personal Wallets?
This is likely to be one of the biggest questions for Kenyan cryptocurrency users.
Many people prefer keeping cryptocurrency in wallets they control directly rather than leaving funds on exchanges.
Examples include Trust Wallet, MetaMask, and hardware wallets.
These are commonly called self-custody or self-hosted wallets.
Unlike an exchange account, a self-custody wallet does not necessarily involve a company holding the user’s private keys or operating the wallet on their behalf.
Under FATF’s approach, a person does not automatically become a regulated virtual asset service provider merely because they hold or transfer cryptocurrency for themselves.
That is an important distinction.
However, when a regulated exchange sends cryptocurrency to a self-hosted wallet or receives funds from one, the exchange may still have obligations involving customer verification, monitoring, and risk assessment.
Some countries have adopted additional rules for these transactions.
Whether Kenya introduces similar requirements, and how far they extend, will depend on the final legal provisions and guidance.
For now, it would be misleading to claim that the IMF’s recommendation means every Trust Wallet or MetaMask user must register their personal wallet with the Kenyan government.
That has not been established by the reported recommendation.
Could Crypto Platforms Share Your National ID With the Government?
Potentially, certain identifying information could be made available to competent authorities under applicable laws.
But there is an important difference between sharing information between regulated institutions and automatically forwarding every customer’s identity to a government database.
The FATF Travel Rule primarily concerns the secure transmission of required information between financial service providers involved in a transfer.
Separately, regulated businesses may have legal obligations to report suspicious transactions to financial intelligence authorities.
In Kenya, the Financial Reporting Centre receives and analyses suspicious transaction reports.
The IMF recommendation aims to improve the information available for these checks.
However, the precise conditions under which customer information would be transmitted to the FRC, requested by authorities, or retained by service providers would need to be determined by Kenya’s legal framework.
It should not be assumed that every crypto transfer would automatically trigger a report containing the full identification details of both parties.
There is also a legitimate privacy concern.
Personal information such as national ID numbers, physical addresses, and financial transaction histories can be sensitive.
If collected and exchanged without adequate safeguards, that data could create risks of unauthorised access, identity theft, and misuse.
For this reason, stronger monitoring requirements should be accompanied by clear rules on data security, access controls, retention, and lawful disclosure.
Preventing financial crime should not require abandoning basic protections for legitimate users.
Could the New Rules Affect Crypto Businesses in Kenya?
Yes, particularly businesses that process transfers between different cryptocurrency platforms.
For exchanges and other regulated service providers, Travel Rule compliance may require additional technology and operational processes.
They may need systems that can identify counterparties, securely exchange required customer information, and detect incomplete or suspicious transfers.
They may also need to coordinate with foreign exchanges that operate under different regulatory requirements.
For smaller Kenyan cryptocurrency businesses, these systems could introduce additional compliance costs.
That could be particularly challenging for companies operating with limited resources.
On the other hand, clear and internationally aligned requirements may help legitimate crypto businesses develop stronger relationships with banks, payment providers, and international partners.
Financial institutions are often cautious about working with businesses whose transaction-monitoring systems they cannot assess.
A more predictable compliance framework could reduce some of those concerns, although it would not guarantee banking access.
The outcome will depend heavily on how the requirements are implemented.
What Happens to Peer-to-Peer Crypto Trading?
Peer-to-peer trading, commonly called P2P, allows people to buy and sell cryptocurrency directly with one another.
For example, one person might sell USDT to another person in exchange for payment through M-Pesa.
P2P activity has become a familiar part of Kenya’s cryptocurrency market.
But it also presents difficult questions for regulators.
A transaction between two people using their own wallets is not necessarily the same as a transfer processed by two regulated exchanges.
FATF’s standards focus on virtual asset service providers and other covered institutions.
A person making an occasional transfer or trading their own assets does not automatically become a regulated service provider.
However, a business that regularly facilitates exchanges, handles customer funds, or carries out covered virtual asset activities may fall within regulatory requirements, depending on its operations and the law.
This means the consequences for P2P trading cannot be reduced to a simple statement that all P2P transfers will be monitored or banned.
The IMF’s reported recommendation does not establish such a ban.
Kenya will need to clarify how its rules distinguish ordinary individuals using digital assets from businesses providing regulated crypto services.
Could This Make Crypto Safer for Kenyans?
There are reasons to believe that better information-sharing could help combat certain types of financial crime.
Imagine a fraudster convincing a Kenyan investor to send cryptocurrency to an account controlled by a criminal network.
If the receiving exchange has reliable identifying information and effective monitoring systems, it may have a better opportunity to detect suspicious activity or respond to a lawful investigation.
Similarly, exchanges may be better equipped to screen transactions involving sanctioned individuals or suspicious counterparties.
But the Travel Rule is not a complete solution to crypto fraud.
Criminals can use stolen identities, unregulated platforms, compromised accounts, and other methods to evade detection.
And even when a transaction can be traced, recovering stolen cryptocurrency may remain difficult.
The Travel Rule could improve the information available for investigations, but it does not guarantee that fraudulent transactions will be stopped or that victims will recover their funds.
It is one part of a broader financial-crime prevention system.
Frequently Asked Questions (FAQs)
1. Does the IMF want Kenya to identify everyone using cryptocurrency?
The IMF reportedly wants regulated cryptocurrency service providers to collect and securely exchange required information about senders and recipients during covered transfers. This does not automatically mean everyone who owns cryptocurrency must register with the government.
2. What is the Crypto Travel Rule?
The Crypto Travel Rule is an international financial-crime prevention standard requiring covered cryptocurrency service providers to obtain and transmit identifying information about people sending and receiving digital assets.
3. Will my national ID number appear on the blockchain?
No. The Travel Rule does not require personal identification details to be published on public blockchains. Required information is generally transmitted through secure arrangements between regulated institutions.
4. Will this affect Binance users in Kenya?
It could affect transactions involving Binance or other exchanges where applicable Travel Rule obligations apply. The exact requirements will depend on the laws governing the platforms and the nature of the transfers.
5. Will Kenya ban Trust Wallet or MetaMask?
There is no evidence that the IMF’s reported Travel Rule recommendation requires Kenya to ban self-custody wallets. Transfers involving regulated providers and self-hosted wallets may still be subject to certain compliance checks.
6. Is the Travel Rule already law in Kenya?
Kenya has an existing virtual asset regulatory framework and broader anti-money-laundering obligations. The latest IMF recommendation reportedly identifies a gap in the explicit requirement to transmit sender and recipient information during covered crypto transfers. The precise scope and implementation of any additional binding requirements require confirmation through current legal instruments.
7. Why is the IMF pushing for these changes?
The stated objective is to help cryptocurrency service providers and financial authorities identify suspicious transfers, conduct sanctions screening, and reduce the risk of money laundering and terrorist financing.
8. Can the government track all Bitcoin transactions?
Bitcoin transactions are publicly visible on the blockchain, but wallet addresses do not automatically identify their owners. Authorities can sometimes link transactions to individuals using exchange records, blockchain analysis, and other evidence. The Travel Rule could strengthen that process for transfers involving regulated platforms.